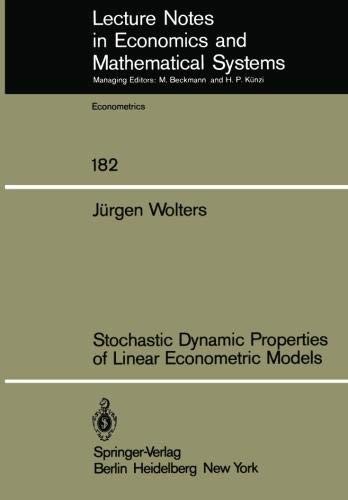
Stochastic Dynamic Properties of Linear Econometric Models
0
0
As an Amazon Associate and affiliate partner, Menrva Books earns from qualifying purchases. Learn more
Author Description
Author description coming soon. We're reaching out to them in the ether...
Menrva's Summary
THE THESIS
This book investigates the stochastic dynamic properties of linear econometric models, focusing on the theoretical underpinnings and practical applications of these models in economic analysis. The author, J. Wolters, draws upon established econometric theory to present a rigorous examination of model behavior under uncertainty. The work aims to provide a comprehensive framework for understanding how random shocks propagate through linear economic systems and influence their long-term dynamics.
THE SCOPE MAP
- Analysis of linear econometric models with stochastic components.
- Theoretical frameworks for understanding dynamic properties.
- Methods for simulating and analyzing model responses to shocks.
- Applications in economic forecasting and policy analysis.
THE AUTHORITY PERSPECTIVE
This work is likely to be regarded as a specialized academic text within the field of econometrics. Its focus on theoretical properties suggests a dense, technical presentation aimed at researchers and advanced students. The subject matter points to a rigorous exploration of mathematical and statistical techniques applied to economic modeling, offering a foundational resource for those engaged in quantitative economic research.
Page Count:
156
Publication Date:
1980-01-01
ISBN-10:
354010240X
ISBN-13:
9783540102403
Science
Economics
Non-Fiction
Mathematical Economics
Econometrics
Community Tags
Similar Books