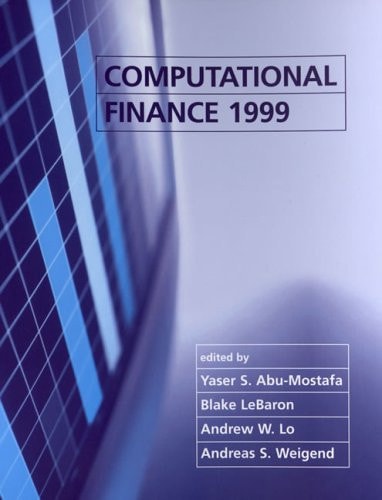
Computational Finance 1999
0
0
As an Amazon Associate and affiliate partner, Menrva Books earns from qualifying purchases. Learn more
Author Description
Covers the techniques of data mining, knowledge discovery, genetic algorithms, neural networks, bootstrapping, machine learning and Monte Carlo simulation. These methods are applied to a range of problems in finance, including risk management, asset allocation, style analysis, dynamic trading and hedging, forecasting and option pricing. The book is based on the sixth annual international conference Computational Finance 1999, held at New York University's Stern School of Business.
Menrva's Summary
THE THESIS
This book explores the application of advanced computational techniques to complex financial problems. It details methods such as data mining, genetic algorithms, neural networks, and Monte Carlo simulation, drawing from the proceedings of the 1999 International Conference on Computational Finance. The content focuses on practical applications in areas including risk management, asset allocation, and option pricing, providing insights into the quantitative approaches shaping modern finance.
THE SCOPE MAP
- Techniques of data mining and knowledge discovery
- Applications of genetic algorithms and neural networks
- Methods of bootstrapping and machine learning
- Use of Monte Carlo simulation in finance
- Problem areas: risk management and asset allocation
- Problem areas: style analysis and dynamic trading
- Problem areas: forecasting and option pricing
- Content derived from the 1999 International Conference on Computational Finance
THE AUTHORITY PERSPECTIVE
The book compiles research presented at a specialized conference, indicating a focus on advanced, quantitative methods within computational finance. The subject matter suggests a technical audience interested in the intersection of computer science and financial modeling. The inclusion of diverse techniques like genetic algorithms and neural networks points to a broad exploration of modern analytical tools. The application areas covered, from risk management to option pricing, highlight the practical relevance of these computational approaches in the financial industry.
Page Count:
650
Publication Date:
2000-05-01
Publisher:
The MIT Press
ISBN-10:
0262011786
ISBN-13:
9780262011785
Non-Fiction
Science & Technology
Machine Learning
Data Mining
Asset Allocation
Community Tags
Similar Books