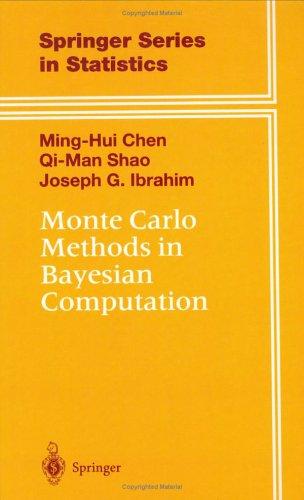
Monte Carlo Methods In Bayesian Computation
0
0
As an Amazon Associate and affiliate partner, Menrva Books earns from qualifying purchases. Learn more
Author Description
Author description coming soon. We're reaching out to them in the ether...
Menrva's Summary
THE THESIS
This book explores the application of Monte Carlo methods to Bayesian computation. It details the theoretical underpinnings and practical implementation of these stochastic simulation techniques for solving complex problems in Bayesian statistics. The text aims to provide readers with a comprehensive understanding of how to leverage Monte Carlo approaches for parameter estimation, model comparison, and posterior inference in Bayesian frameworks.
THE SCOPE MAP
- Detailed explanation of Markov Chain Monte Carlo (MCMC) algorithms
- Discussion of various sampling techniques, including Gibbs sampling and Metropolis-Hastings
- Applications in hierarchical modeling and complex statistical models
- Methods for assessing convergence and diagnosing MCMC output
- Exploration of particle filtering and sequential Monte Carlo methods
- Case studies demonstrating practical implementation in R and other statistical software
- Theoretical foundations of Bayesian inference and probability theory
THE AUTHORITY PERSPECTIVE
The book is recognized as a foundational text for researchers and practitioners in computational statistics and Bayesian inference. Its strength lies in its rigorous treatment of Monte Carlo methods and their direct application to Bayesian problems. The detailed explanations and practical examples make it a valuable resource for those seeking to implement these advanced computational techniques. It is often cited for its clear exposition of complex algorithms and their theoretical justification.
Page Count:
0
Publication Date:
1900-01-01
Publisher:
Springer
ISBN-10:
1461212774
ISBN-13:
9781461212775
Non-Fiction
Science
Bayesian Statistics
Monte Carlo Methods
Computational statistics
Community Tags
Similar Books