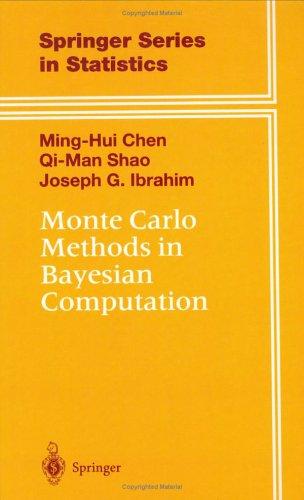
Monte Carlo Methods in Bayesian Computation
0
0
As an Amazon Associate and affiliate partner, Menrva Books earns from qualifying purchases. Learn more
Author Description
This book examines advanced Bayesian computational methods, it presents methods for sampling from posterior distributions and discusses how to compute posterior quantities of interest using Markov Chain Monte Carlo (MCMC) samples. This book examines each of these issues in detail and heavily focuses on computing various posterior summaries from a given MCMC sample. The book presents and equal mixture of theory and applications involving real data. It is intended as a graduate textbook or a reference book for a one-semester course at the advanced master's or Ph.D. level. It would also serve as a useful reference book for applied or theoretical researchers as well as practitioners.--BOOK JACKET.
Menrva's Summary
THE THESIS
This book investigates the application of Monte Carlo methods to complex Bayesian computational problems. It details techniques for sampling from posterior distributions and computing essential posterior quantities using Markov Chain Monte Carlo (MCMC) samples, with a strong emphasis on deriving various posterior summaries from these samples. The work balances theoretical foundations with practical applications using real-world data, making it suitable for advanced graduate studies or as a reference for researchers and practitioners.
THE SCOPE MAP
- Methods for sampling from posterior distributions
- Computation of posterior quantities of interest using MCMC samples
- Detailed examination of sampling and computation issues
- Focus on computing various posterior summaries from MCMC samples
- Integration of theory and real-data applications
- Suitable for advanced master's or Ph.D. level courses
- Reference for applied and theoretical researchers
THE AUTHORITY PERSPECTIVE
The book is positioned as a graduate textbook or a reference for advanced study in Bayesian computation, suggesting a rigorous and comprehensive treatment of its subject matter. Its focus on both theory and real-data applications indicates an aim to bridge the gap between academic concepts and practical implementation in statistical research and practice. The detailed examination of MCMC methods and posterior summaries points to its utility for those needing to perform complex statistical analyses.
Page Count:
386
Publication Date:
2001-01-01
ISBN-10:
0387989358
ISBN-13:
9780387989358
Non-Fiction
Science
Statistics
Computational statistics
Monte Carlo Methods
Bayesian Statistics
Community Tags
Similar Books