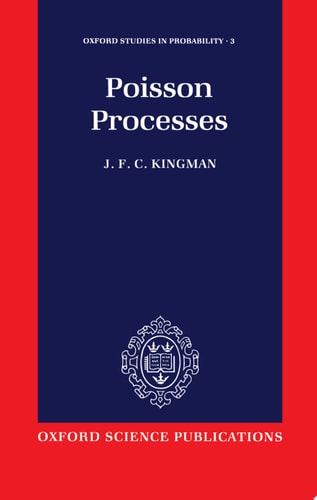
Poisson Processes
0
0
As an Amazon Associate and affiliate partner, Menrva Books earns from qualifying purchases. Learn more
Author Description
Two fundamental theories are commonly debated in the study of random processes: the Bachelier Wiener model of Brownian motion, which has been the subject of many books, and the Poisson process. While nearly every book mentions the Poisson process, most hurry past to more general point processes or to Markov chains. This comparative neglect is ill judged, and stems from a lack of perception of the real importance of the Poisson process. This distortion partly comes about from a restriction to one dimension, while the theory becomes more natural in more general contexts. This book attempts to redress the balance. It records the author's fascination with the beauty and wide applicability of Poisson processes in one or more dimensions. The mathematical theory is powerful and a few key results often produce surprising consequences.
Menrva's Summary
THE THESIS
This text investigates the mathematical significance and broad applicability of Poisson processes, arguing that they are frequently undervalued in favor of other random process models. J. F. C. Kingman, a prominent mathematician, draws upon his extensive research to demonstrate that the Poisson process is a foundational element of probability theory. By moving beyond the traditional one-dimensional constraints, the author presents a comprehensive framework that highlights the inherent beauty and utility of these processes in multidimensional contexts.
THE SCOPE MAP
What You Will Find
- Theoretical foundations of Poisson processes in one or more dimensions
- Comparative analysis between Brownian motion and Poisson models
- Mathematical proofs and key results regarding point processes
- Applications of Poisson theory in broader stochastic modeling
THE AUTHORITY PERSPECTIVE
Experts recognize this work as a definitive text for those seeking a deeper understanding of Poisson processes beyond introductory treatments. Readers frequently note the mathematical rigor and the author's ability to clarify complex stochastic concepts.
Page Count:
112
Publication Date:
1993-01-28
Publisher:
Clarendon Press
ISBN-10:
0198536933
ISBN-13:
9780198536932
Science
Mathematics
Statistics
Stochastic processes
Probability