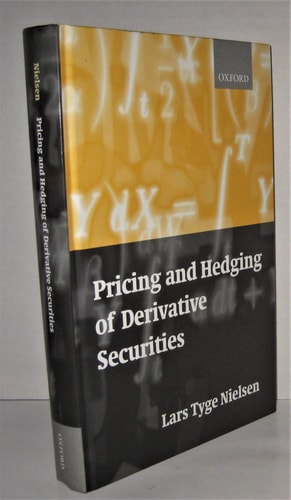
Pricing and Hedging of Derivative Securities
0
0
As an Amazon Associate and affiliate partner, Menrva Books earns from qualifying purchases. Learn more
Author Description
The theory of pricing and hedging of derivative securities is mathematically sophisticated. This book is an introduction to the use of advanced probability theory in financial economics, presenting the necessary mathematics in a precise and rigorous manner. It enables the reader to understand journal literature with confidence, to apply the methods to new problems or to do original research in the field.
Menrva's Summary
THE THESIS
This text investigates the mathematical foundations required for the pricing and hedging of derivative securities within the framework of financial economics. The author, Lars Tyge Nielsen, provides a rigorous introduction to advanced probability theory tailored for financial applications. By establishing a precise mathematical baseline, the book enables readers to navigate complex journal literature and conduct independent research in quantitative finance.
THE SCOPE MAP
What You Will Find
- Advanced probability theory applied to financial markets
- Mathematical frameworks for derivative pricing models
- Hedging strategies and risk management methodologies
- Theoretical foundations for original research in financial economics
THE AUTHORITY PERSPECTIVE
Experts recognize this work as a rigorous, high-level introduction suitable for those with a strong background in mathematics. Readers frequently note the academic density of the prose, which serves as a foundational text for students and researchers entering the field of quantitative finance.
Page Count:
464
Publication Date:
1999-01-01
Publisher:
Oxford University Press
ISBN-10:
0198776195
ISBN-13:
9780198776192
Economics
Mathematics
Investment
Derivatives
Finance
Community Tags
Similar Books