Probability and Random Processes with One Thousand Exercises in Probability
0
0
As an Amazon Associate and affiliate partner, Menrva Books earns from qualifying purchases. Learn more
Author Description
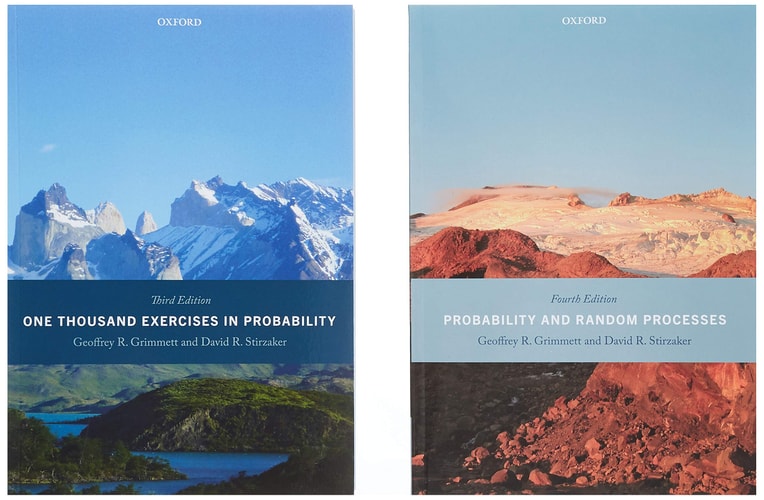
Probability and Random Processes begins with the basic ideas common to most undergraduate courses in mathematics, statistics, and science. It ends with material usually found at graduate level, for example, Markov processes, (including Markov chain Monte Carlo), martingales, queues, diffusions, (including stochastic calculus with Itô's formula), renewals, stationary processes (including the ergodic theorem), and option pricing in mathematical finance using the Black-Scholes formula. Further, in this new revised fourth edition, there are sections on coupling from the past, Lévy processes, self-similarity and stability, time changes, and the holding-time/jump-chain construction of continuous-time Markov chains. Finally, the number of exercises and problems has been increased by around 300 to a total of about 1317, and many of the existing exercises have been refreshed by additional parts. The solutions to these exercises and problems can be found in the companion volume, One Thousand Exercises in Probability, third edition.One Thousand Exercises in Probability, third edition is a revised, updated, and greatly expanded version of previous edition of 2001. The 1300+ exercises contained within are not merely drill problems, but have been chosen to illustrate the concepts, illuminate the subject, and both inform and entertain the reader. A broad range of subjects is covered, including elementary aspects of probability and random variables, sampling, generating functions, Markov chains, convergence, stationary processes, renewals, queues, martingales, diffusions, Lévy processes, stability and self-similarity, time changes, and stochastic calculus including option pricing via the Black-Scholes model of mathematical finance.
Menrva's Summary
THE THESIS
This text investigates the foundational principles and advanced applications of probability theory and random processes through a comprehensive pedagogical framework. Authors David Stirzaker and Geoffrey Grimmett, both established experts in the field of probability, provide a structured progression from undergraduate-level concepts to graduate-level research topics. The work integrates theoretical rigor with an extensive collection of problems designed to reinforce mathematical intuition and technical proficiency.
THE SCOPE MAP
What You Will Find
- Comprehensive coverage of Markov processes, martingales, and stochastic calculus including Itô's formula.
- Advanced topics such as Lévy processes, ergodic theorems, and option pricing via the Black-Scholes model.
- A vast repository of over 1300 exercises ranging from elementary probability to complex random variables.
- Methodological focus on the holding-time and jump-chain construction of continuous-time Markov chains.
THE AUTHORITY PERSPECTIVE
Experts and academics widely recognize this work as a standard reference for students and researchers in mathematics and quantitative finance. Readers frequently note the high density of the material and the necessity of the companion solutions volume for mastering the complex problem sets provided.
Page Count:
1168
Publication Date:
2020-09-16
Publisher:
Oxford University Press
ISBN-10:
0198847629
ISBN-13:
9780198847625
Mathematics
Finance
New Used & Rental Textbooks
Probability
Statistics
Applied
Stochastic processes
Community Tags
Similar Books