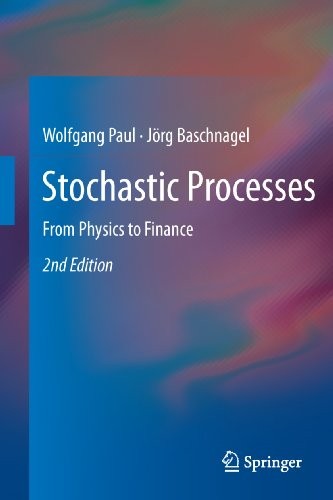
Stochastic Processes: From Physics to Finance
0
0
As an Amazon Associate and affiliate partner, Menrva Books earns from qualifying purchases. Learn more
Author Description
This book introduces the theory of stochastic processes with applications taken from physics and finance. Fundamental concepts like the random walk or Brownian motion but also Levy-stable distributions are discussed. Applications are selected to show the interdisciplinary character of the concepts and methods. In the second edition of the book a discussion of extreme events ranging from their mathematical definition to their importance for financial crashes was included. The exposition of basic notions of probability theory and the Brownian motion problem as well as the relation between conservative diffusion processes and quantum mechanics is expanded. The second edition also enlarges the treatment of financial markets. Beyond a presentation of geometric Brownian motion and the Black-Scholes approach to option pricing as well as the econophysics analysis of the stylized facts of financial markets, an introduction to agent based modeling approaches is given.
Menrva's Summary
THE THESIS
This book investigates the theory and application of stochastic processes across physics and finance. It builds upon fundamental concepts such as random walks, Brownian motion, and Levy-stable distributions, demonstrating their interdisciplinary relevance. The second edition enhances the discussion of extreme events, their mathematical definitions, and their role in financial crashes, while also expanding on the relationship between diffusion processes and quantum mechanics. Furthermore, it deepens the treatment of financial markets with new sections on agent-based modeling approaches alongside existing coverage of geometric Brownian motion and the Black-Scholes model.
THE SCOPE MAP
- Introduction to the theory of stochastic processes.
- Discussion of fundamental concepts: random walk, Brownian motion, Levy-stable distributions.
- Applications in physics, including conservative diffusion processes and quantum mechanics.
- Applications in finance, covering geometric Brownian motion and the Black-Scholes model.
- Inclusion of extreme events, their mathematical definition, and relevance to financial crashes (second edition).
- Expansion on basic notions of probability theory and the Brownian motion problem.
- Introduction to agent-based modeling approaches in financial markets (second edition).
THE AUTHORITY PERSPECTIVE
The second edition of Wolfgang Paul's "Stochastic Processes: From Physics to Finance" expands upon its foundational exploration of stochastic theory with updated and augmented content. The inclusion of extreme events and agent-based modeling in financial markets, alongside a more detailed exposition of diffusion processes and quantum mechanics, suggests a text aimed at readers seeking a comprehensive understanding of these complex topics. The book's interdisciplinary approach, bridging physics and finance, positions it as a valuable resource for advanced students and researchers in quantitative fields.
Page Count:
280
Publication Date:
2013-01-01
ISBN-10:
3319003275
ISBN-13:
9783319003276
Non-Fiction
Economics
Science
Mathematical Physics
Stochastic processes
Probability Theory
Community Tags
Similar Books