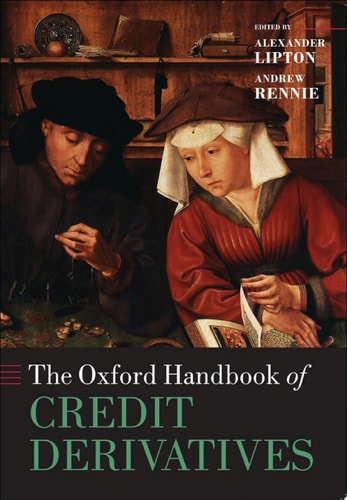
Oxford Handbook of Credit Derivatives
0
0
As an Amazon Associate and affiliate partner, Menrva Books earns from qualifying purchases. Learn more
Author Description
From The Late 1990s, The Spectacular Growth Of A Secondary Market For Credit Through Derivatives Has Been Matched By The Emergence Of Mathematical Modelling Analysing The Credit Risk Embedded In These Contracts. This Book Aims To Provide A Broad And Deep Overview Of This Modelling, Covering Statistical Analysis And Techniques, Modelling Of Default Of Both Single And Multiple Entities, Counterparty Risk, Gaussian And Non-gaussian Modelling, And Securitisation. Both Reduced-form And Firm-value Models For The Default Of Single Entities Are Considered In Detail, With Extensive Discussion Of Both Their Theoretical Underpinnings And Practical Usage In Pricing And Risk. For Multiple Entity Modelling, The Now Notorious Gaussian Copula Is Discussed With Analysis Of Its Shortcomings, As Well As A Wide Range Of Alternative Approaches Including Multivariate Extensions To Both Firm-value And Reduced Form Models, And Continuous-time Markov Chains. One Important Case Of Multiple Entities Modelling - Counterparty Risk In Credit Derivatives - Is Further Explored In Two Dedicated Chapters. Alternative Non-gaussian Approaches To Modelling Are Also Discussed, Including Extreme-value Theory And Saddle-point Approximations To Deal With Tail Risk. Finally, The Recent Growth In Securitisation Is Covered, Including House Price Modelling And Pricing Models For Asset-backed Cdos. The Current Credit Crisis Has Brought Modelling Of The Previously Arcane Credit Markets Into The Public Arena. Lipton And Rennie With Their Excellent Team Of Contributors, Provide A Timely Discussion Of The Mathematical Modelling That Underpins Both Credit Derivatives And Securitisation. Though Technical In Nature, The Pros And Cons Of Various Approaches Attempt To Provide A Balanced View Of The Role That Mathematical Modelling Plays In The Modern Credit Markets. This Book Will Appeal To Students And Researchers In Statistics, Economics, And Finance, As Well As Practitioners, Credit Traders, And Quantitative Analysts
Menrva's Summary
THE THESIS
This volume investigates the mathematical frameworks and statistical methodologies required to model credit risk within the secondary market for credit derivatives. Alexander Lipton and a team of contributors synthesize theoretical underpinnings with practical applications, addressing the complexities of default modeling, counterparty risk, and securitization. The text evaluates the efficacy and limitations of various quantitative models, particularly in the context of market volatility and the credit crisis.
THE SCOPE MAP
What You Will Find
- Mathematical models for single and multiple entity default, including reduced-form and firm-value approaches.
- Analysis of the Gaussian copula and its alternatives, such as multivariate extensions and continuous-time Markov chains.
- Techniques for addressing tail risk, including extreme-value theory and saddle-point approximations.
- Coverage of securitization, house price modeling, and asset-backed CDO pricing.
Scope Limits
- The text focuses primarily on the mathematical and quantitative aspects of credit derivatives rather than regulatory or legal frameworks.
- It assumes a high level of prior knowledge in statistics and financial mathematics.
THE AUTHORITY PERSPECTIVE
Experts and practitioners recognize this work as a rigorous technical resource for quantitative analysts and researchers navigating the complexities of credit markets. Readers frequently note the high academic density of the prose, which serves as a specialized reference for those already familiar with advanced financial engineering.
Page Count:
704
Publication Date:
2011-01-01
Publisher:
Oxford University Press
ISBN-10:
0191648248
ISBN-13:
9780191648243
Economics
Credit Derivatives
Mathematics
Finance
Statistics
Community Tags
Similar Books