Capital Allocation
0
0
As an Amazon Associate and affiliate partner, Menrva Books earns from qualifying purchases. Learn more
Author Description
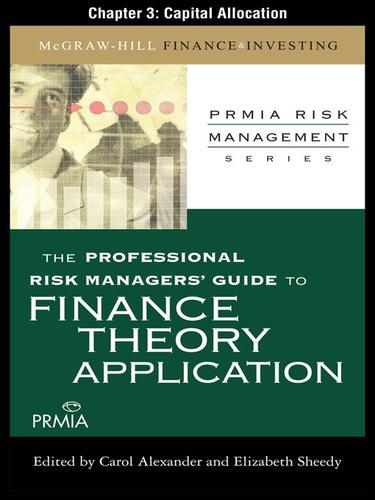
The following is a chapter from The Professional Risk Managers' Guide to Finance Theory and Application, a complete reference for managing risk in all areas of finance, from insurance and banking to asset management and institutional investing. Ten experts from around the world discuss every aspect of finance theory and how it is intertwined with the process of risk management. This reference delivers a comprehensive introduction to portfolio mathematics that includes discussion of the efficient frontier, portfolio theory, and the concept of portfolio diversification.
Menrva's Summary
THE THESIS
The core challenge of this chapter is to elucidate the principles and practices of effective capital allocation within the broader framework of financial risk management. This chapter, drawn from a comprehensive reference work, addresses the critical intersection of finance theory and risk management. It features contributions from ten international experts, offering insights into portfolio mathematics, including the efficient frontier, portfolio theory, and diversification strategies. The text aims to provide a thorough understanding of how capital is allocated to manage risk across diverse financial sectors.
THE SCOPE MAP
- Detailed discussion of capital allocation strategies in finance.
- Expert analysis from ten international finance and risk management professionals.
- Exploration of portfolio mathematics, including the efficient frontier.
- In-depth coverage of portfolio theory and its practical applications.
- Explanation of the concept and importance of portfolio diversification.
- Application of risk management principles to insurance, banking, and asset management.
- Integration of finance theory with real-world risk management scenarios.
THE AUTHORITY PERSPECTIVE
This chapter, as part of a larger reference work, is positioned as a key resource for professionals seeking to understand the intricate relationship between capital allocation and financial risk management. The inclusion of multiple expert perspectives suggests a comprehensive and authoritative treatment of the subject matter. The focus on established theories like the efficient frontier and portfolio diversification indicates a text grounded in academic principles, intended for serious practitioners and students of finance.
Page Count:
0
Publication Date:
2010-01-01
ISBN-10:
0071731822
ISBN-13:
9780071731829
Business
Non-Fiction
Investment
Finance
Community Tags
Similar Books