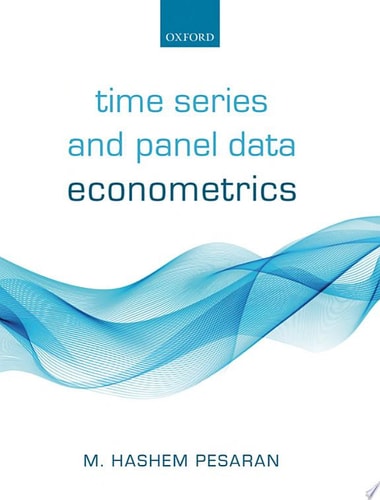
Time Series and Panel Data Econometrics
0
0
As an Amazon Associate and affiliate partner, Menrva Books earns from qualifying purchases. Learn more
Author Description
This book is concerned with recent developments in time series and panel data techniques for the analysis of macroeconomic and financial data. It provides a rigorous, nevertheless user-friendly, account of the time series techniques dealing with univariate and multivariate time series models, as well as panel data models.It is distinct from other time series texts in the sense that it also covers panel data models and attempts at a more coherent integration of time series, multivariate analysis, and panel data models. It builds on the author's extensive research in the areas of time series and panel data analysis and covers a wide variety of topics in one volume. Different parts of the book can be used as teaching material for a variety of courses in econometrics. It can also be used as reference manual.It begins with an overview of basic econometric and statistical techniques, and provides an account of stochastic processes, univariate and multivariate time series, tests for unit roots, cointegration, impulse response analysis, autoregressive conditional heteroskedasticity models, simultaneous equation models, vector autoregressions, causality, forecasting, multivariate volatility models, panel data models, aggregation and global vector autoregressive models (GVAR). The techniques are illustrated using Microfit 5 (Pesaran and Pesaran, 2009, OUP) with applications to real output, inflation, interest rates, exchange rates, and stock prices.
Menrva's Summary
THE THESIS
This book investigates the integration of time series and panel data techniques to provide a comprehensive framework for analyzing macroeconomic and financial datasets. M. Hashem Pesaran, a prominent researcher in the field, draws upon his extensive academic work to synthesize univariate, multivariate, and panel data models into a single, coherent volume. The text serves as both a pedagogical tool for advanced econometrics courses and a practical reference manual for empirical researchers.
THE SCOPE MAP
What You Will Find
- Comprehensive coverage of stochastic processes, unit root tests, and cointegration analysis.
- Methodologies for vector autoregressions, causality testing, and multivariate volatility modeling.
- Advanced panel data techniques including global vector autoregressive models (GVAR).
- Practical application of econometric theory using Microfit 5 software to analyze real-world financial indicators.
THE AUTHORITY PERSPECTIVE
Experts recognize this work as a rigorous and cohesive resource that bridges the gap between traditional time series analysis and modern panel data econometrics. Readers frequently note the technical density of the prose, which is best suited for graduate-level students and professional economists.
Page Count:
592
Publication Date:
2015-11-17
Publisher:
Oxford University Press
ISBN-10:
0198736916
ISBN-13:
9780198736912
Economics
Mathematics
Finance
Econometrics
Statistics
Community Tags
Other Editions(3)

Similar Books