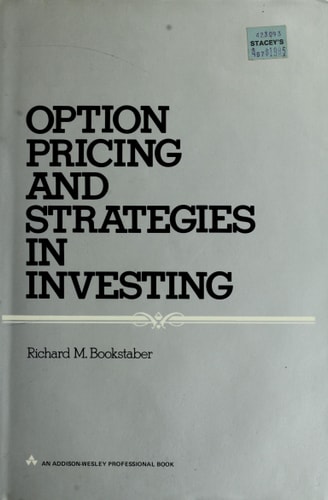
Option Pricing and Strategies in Investing
0
0
As an Amazon Associate and affiliate partner, Menrva Books earns from qualifying purchases. Learn more
Author Description
Option pricing and strategies in investing
Menrva's Summary
THE THESIS
This book investigates the mathematical foundations of option pricing and the practical application of various hedging and speculative strategies within financial markets. Richard M. Bookstaber, an experienced practitioner in quantitative finance, utilizes a blend of theoretical models and market-based evidence to explain how options function as instruments for risk management. The text provides a framework for understanding the relationship between underlying asset volatility, time decay, and the strategic deployment of derivative contracts.
THE SCOPE MAP
What You Will Find
- Mathematical models for determining the fair value of options
- Strategic applications of calls, puts, and complex spreads
- Analysis of market volatility and its impact on pricing
- Risk management techniques for individual and institutional portfolios
THE AUTHORITY PERSPECTIVE
Experts frequently cite this work as a foundational text for those seeking to understand the mechanics of derivative pricing. Readers often note the technical density of the prose, which requires a solid grasp of financial mathematics to fully comprehend the presented strategies.
Page Count:
222
Publication Date:
1981-01-01
Publisher:
Addison Wesley Pub. Co
ISBN-10:
0201001233
ISBN-13:
9780201001235
Business
Finance
Investing
Community Tags
Similar Books